What Is Escrow? The Two Kinds Every Home Buyer Meets (Explained Simply)
Escrow is the trusted middle-person of home buying — twice. Here is why your payment changed and what a shortage really means.
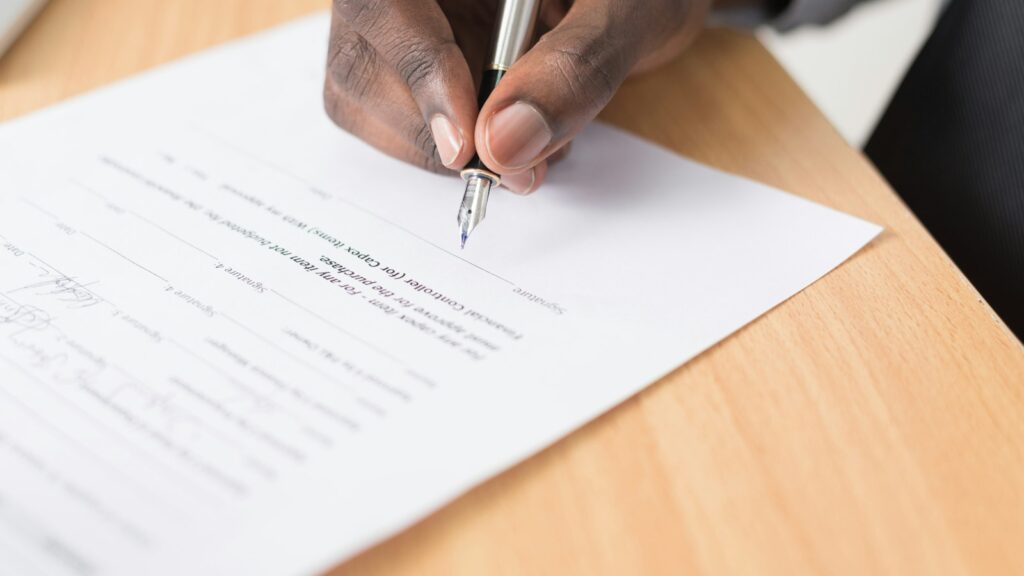
- Escrow during the sale: a neutral third party holds money and documents until everyone does their part.
- Escrow account after closing: your lender collects part of each payment and pays your property taxes and home insurance for you.
- Your payment can change each year after an escrow analysis, even with a fixed-rate loan.
Escrow is the referee of home buying. Nobody gets the ball until the rules are followed. The confusing part is that the same word is used for two different referees. Let’s meet both.
Kind #1: Escrow during the home purchase
When your offer is accepted, you usually put down earnest money to show you are serious. It does not go to the seller. It goes to a neutral escrow or title company (in some states, an attorney) who holds it until closing.
The escrow holder also collects documents, the down payment and loan funds, then releases everything at closing: the seller gets paid, you get the keys, and the deed is recorded.
Kind #2: Your escrow account (after you buy)
Most lenders set up an escrow account so your property taxes and homeowners insurance never go unpaid. Each month, your payment includes:
- Principal and interest (paying back the loan)
- One-twelfth of your yearly property tax
- One-twelfth of your yearly homeowners insurance
- Sometimes mortgage insurance or flood insurance
Why did my payment go up? (The escrow analysis)
Once a year, your servicer reviews the account. If taxes or insurance went up, your monthly escrow amount goes up too — even though your interest rate never changed.
- Shortage: the account did not have enough. You can usually pay the shortage in one lump sum or spread it over the next 12 months.
- Surplus: the account had too much. Federal rules generally require the servicer to refund surpluses of $50 or more.
The escrow cushion
Servicers may keep a small cushion so the account doesn’t run dry. Federal rules (RESPA) generally cap it at one-sixth of the yearly escrow payments — about two months’ worth.
Can I skip the escrow account?
Sometimes. Many lenders let you waive escrow on a conventional loan with enough equity (often 20% or more), sometimes for a small fee or slightly higher rate. FHA, VA and USDA loans generally require escrow. If you waive it, you must budget and pay large tax and insurance bills yourself on time.
| With escrow | Without escrow | |
|---|---|---|
| Who pays taxes & insurance | Your servicer, from your account | You, directly |
| Monthly payment | Higher, but predictable | Lower, but big bills later |
| Risk of missing a bill | Low | Higher if you forget |
See your full monthly payment including taxes and insurance in our mortgage calculator, and estimate the escrow deposit you’ll need at closing with the closing cost calculator.
Keep learning: closing costs explained and pre-approval vs pre-qualification.
FAQ
Is escrow money mine?
Yes. It is your money held to pay your bills. Surpluses are refunded, and leftover funds are returned when the loan is paid off.
Does escrow earn interest?
Some states require interest on escrow accounts; many don’t. Check your state rules and statement.
What happens to escrow when I refinance or sell?
The old account is closed and the balance is refunded to you, usually within a few weeks.
Sources: Consumer Financial Protection Bureau guidance on escrow accounts; Real Estate Settlement Procedures Act (RESPA) / Regulation X escrow rules.
Written by
Shivam Kaushik· IMSHIVA
Founder & Director, QuibbleTech Solutions Pvt Ltd · Editor, Keys & Coffee
Shivam Kaushik is the founder of QuibbleTech Solutions Pvt Ltd and the editor of Keys & Coffee. He is not a licensed loan officer or financial adviser. Every guide here is written in plain English and checked against official sources such as the CFPB, HUD, Fannie Mae, Freddie Mac and the Federal Reserve. For advice on your own loan, talk to a licensed lender.
Keys & Coffee is an independent education site. We are not a lender or mortgage broker, we do not take loan applications or payments, and nothing here is financial advice. This site is not affiliated with Axia Home Loans, Axia Financial, LLC, or Planet Home Lending. Rates and rules change often — always confirm details with a licensed loan officer and check any lender on the NMLS Consumer Access site.
Keep reading
Mortgage Broker vs Bank or Direct Lender: Which Gets You the Better Deal?
A mortgage broker shops many lenders; a direct lender offers its own loans. See how each is paid, when each fits, and…
Rent-to-Own Homes Explained: How They Work, Real Costs and Red Flags
Rent-to-own lets you rent now and buy later at a set price. See how option fees and rent credits work, a worked…
Lender Credits Explained: How to Cut Closing Costs (and When It Backfires)
A lender credit lowers your closing costs in exchange for a slightly higher rate. See the break-even math, when it makes sense…