1 in 7 Buyers Now Buy a Home for the Whole Family. Here’s the Money Math Behind It
14% of buyers bought a multigenerational home in NAR’s 2026 survey. Our math shows pooling family income can roughly double what you qualify for at 7.11%.
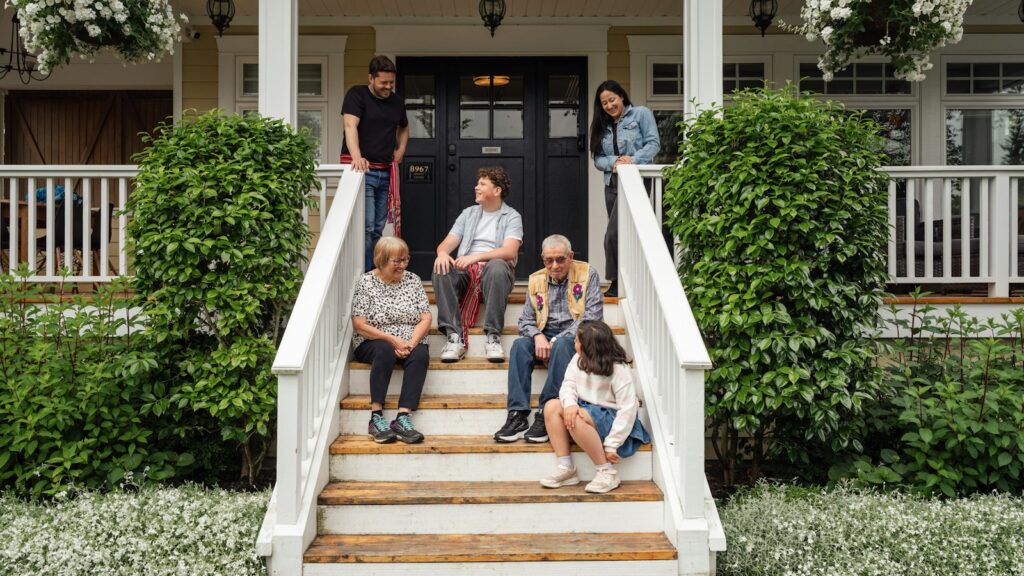
If your Thanksgiving table includes grandparents, grown kids and maybe a boomerang child who never moved out, you are not alone. In the National Association of Realtors’ newest survey, 14% of home buyers bought a multigenerational home, one built for adult children, parents or grandparents under one roof. And the money math explains why: in our example, pooling a parent couple’s income with an adult child’s roughly doubles the home they can qualify for.
- How common: 14% of recent buyers bought a multigenerational home (NAR 2026 Profile).
- Top reasons: caring for aging parents (30%), cost savings (23%), adult kids who never left (19%) or moved back (18%).
- Our math: a $70,000 earner alone qualifies for about a $153,600 loan at 7.11%; adding parents’ $3,800/month Social Security as co-borrowers lifts that to about $311,800.
- Big catch: everyone on the loan is fully responsible for it. Plan who owns what before you sign.
What the new NAR data says
NAR’s 2026 Profile of Home Buyers and Sellers covers purchases from July 2025 to June 2026. As Inman reported from the survey, the share of buyers choosing a multigenerational home held at 14%. The reasons buyers gave:
| Reason for buying a multigenerational home | Share of those buyers |
|---|---|
| Taking care of aging parents | 30% |
| Cost savings | 23% |
| Adult children never left home | 19% |
| Adult children moving back home | 18% |
| More time with aging parents | 18% |
| To afford a bigger home together | 11% |
The same report shows how hard solo buying has become: the median first-time buyer is now 40 years old, matching the record, and 21% of first-time buyers lived at home before buying, up from 12% in 1993. We covered the first-time buyer side in our NAR 2026 first-time buyer breakdown.
The money math: alone vs together
Here is a simple example using the 28% housing guideline, a 30-year fixed at 7.11% (Freddie Mac, Nov. 12, 2026), $600 a month for taxes and insurance, no other debts, and 10% down.
| Who is on the loan | Monthly income | Housing budget (28%) | Loan it supports | Approx. home price |
|---|---|---|---|---|
| Parents only ($3,800/mo Social Security) | $3,800 | $1,064 | $69,000 | $76,600 |
| Adult child only ($70,000 salary) | $5,833 | $1,633 | $153,600 | $170,700 |
| All three together | $9,633 | $2,697 | $311,800 | $346,400 |
Separately, neither household can buy much at today’s rates. Together, they can afford a home around $346,000, still below the national median of $417,500, but in range in many Midwest and Southern markets where NAR’s September median was $329,600 and $361,000.
Ways families set it up
- Co-borrowers: parents and adult child are all on the loan and the title. Easiest way to combine income, but everyone is 100% liable.
- Co-signer: a parent guarantees the loan without living there or owning it. Read co-signing a mortgage first.
- Gift money: parents give part of the down payment and the child buys alone. See gift funds rules.
- Sell and combine: parents sell their paid-off home and put the equity into a larger shared house, often with little or no loan.
Talk about these before you sign
- Who owns what share? Put it in writing, including what happens if someone wants out.
- What if a co-borrower dies? Plan the estate side. Our guide on what happens to a mortgage when you die helps.
- Who pays which bills? Agree on mortgage, repairs, taxes, insurance and utilities.
- Is the home right for aging? A first-floor bedroom and bathroom can matter more than an extra bonus room.
What this means for you
- Adult kids priced out: pooling with family is one of the few ways to buy sooner at 7% rates.
- Parents near or in retirement: think hard before taking on a 30-year debt; consider a smaller share or gifting instead.
- Everyone: run each version in the home affordability calculator and the mortgage calculator before house hunting.
FAQ
Can Social Security income count for a mortgage?
Yes, lenders can count documented Social Security income that is expected to continue. Bring your benefit letter.
Do all co-borrowers need good credit?
Lenders look at every borrower’s credit. A low score from one person can affect the rate or approval, so check everyone’s credit early.
Is a multigenerational home harder to sell later?
Homes with a separate suite or extra bedrooms often appeal to other multigenerational buyers, but local demand varies. Ask a local agent.
Can my parents just add me to their house title?
They can, but it can have tax and legal effects. Talk to an attorney or tax professional first.
Sources: NAR 2026 Profile of Home Buyers and Sellers; Inman; HousingWire; NAR regional medians, Sept. 2026; Freddie Mac PMMS. Affordability math by Keys & Coffee. This article is general education, not financial advice. Keys & Coffee is not a lender.

Written by
Shivam Kaushik· IMSHIVA
Founder & Director, QuibbleTech Solutions Pvt Ltd · Editor, Keys & Coffee
Shivam Kaushik is the founder of QuibbleTech Solutions Pvt Ltd and the editor of Keys & Coffee. He is not a licensed loan officer or financial adviser. Every guide here is written in plain English and checked against official sources such as the CFPB, HUD, Fannie Mae, Freddie Mac and the Federal Reserve. For advice on your own loan, talk to a licensed lender.
Keys & Coffee is an independent education site. We are not a lender or mortgage broker, we do not take loan applications or payments, and nothing here is financial advice. This site is not affiliated with Axia Home Loans, Axia Financial, LLC, or Planet Home Lending. Rates and rules change often — always confirm details with a licensed loan officer and check any lender on the NMLS Consumer Access site.
Keep reading
Gas Is Up 37% From Last Year. Here’s When a Cheaper House Farther Out Stops Being a Deal
Gas is about $4.02 a gallon, up 37% in a year. We ran the drive-until-you-qualify math: a $50K cheaper house 20 miles…
That Record $787 Car Payment Could Cost You About $117,000 in Home-Buying Power
At 7.11%, the average $787 new-car payment uses up about $117,000 of mortgage you could qualify for. See the math by income…
Should I Wait Until 2027 to Sell My House?
Forecasts expect flat prices in 2027. Here is the math of waiting a year and when it does make sense.