Manufactured Home Loans: FHA, Chattel and Mortgage Options
Yes, you can finance a manufactured home. Learn the June 15, 1976 HUD rule, why owning the land matters, and how FHA, conventional and chattel loans compare.
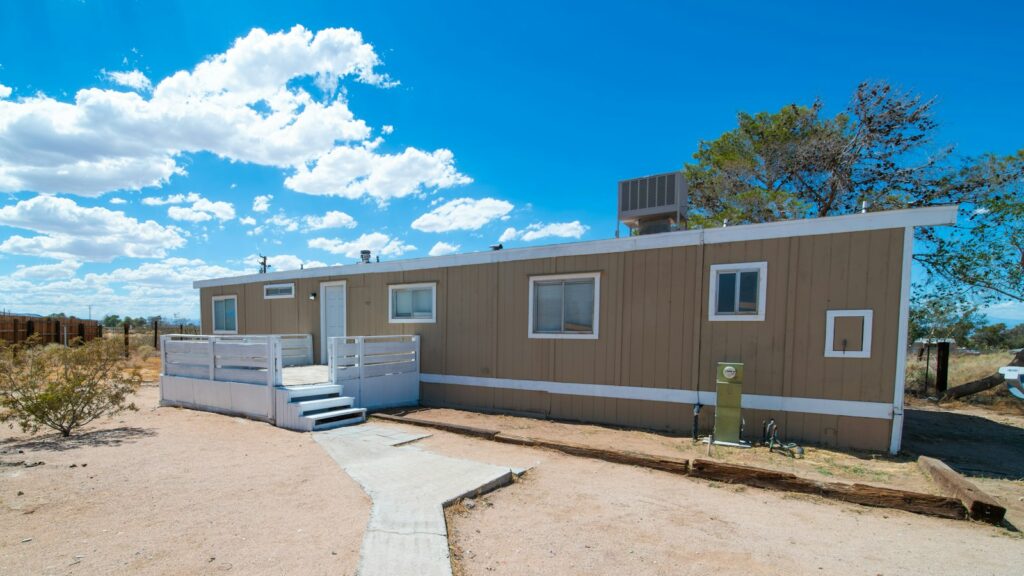
- Yes, you can get a mortgage on a manufactured home if it was built on or after June 15, 1976 and carries a HUD certification label.
- The big question is land. Home + land on a permanent foundation is usually “real property” and can get a normal mortgage. A home on rented land is usually financed with a personal property (“chattel”) loan.
- FHA, VA, USDA and conventional loans can all work for manufactured homes that meet their rules.
- Chattel loans are faster and simpler but usually have higher rates and shorter terms.
- Homes built before June 15, 1976 (“mobile homes”) are generally not eligible for government-backed loans.
Manufactured homes are one of the most affordable ways to own a home in the US. But financing them feels confusing because the rules change depending on one simple thing: is the home tied to land you own? Get that answer first and everything else falls into place.
Manufactured, mobile or modular? The names matter
| Type | What it is | Financing |
|---|---|---|
| Mobile home | Factory-built before June 15, 1976, before federal standards | Hard to finance; not eligible for FHA |
| Manufactured home | Factory-built on or after June 15, 1976 under the federal HUD Code, on a permanent steel chassis | Mortgage or chattel loan, depending on land and foundation |
| Modular home | Factory-built in sections, then built on site to local building codes | Usually financed like a regular site-built home |
Real property vs. personal property
This is the fork in the road:
- Real property: you own (or are buying) the land, the home sits on a permanent foundation, and it is titled as real estate with the land. This is treated much like a regular house and can get a standard mortgage.
- Personal property: the home sits on rented land (for example, a lot in a land-lease community) or isn’t permanently attached. It’s treated more like a vehicle and is usually financed with a chattel loan.
Your loan options
| Loan | Key points |
|---|---|
| FHA (Title II) | Home + land as real estate; permanent foundation meeting HUD’s guide; at least 400 sq ft; your primary home; 3.5% down with a 580+ score |
| FHA Title I | Can finance the home alone, even on a leased lot, if lease rules are met; smaller loan limits |
| Conventional (Fannie Mae / Freddie Mac) | Real property titled as real estate; Fannie’s matrix allows up to 97% LTV on a 1-unit principal residence fixed-rate purchase if you qualify |
| VA and USDA | Possible for eligible borrowers when the home meets each program’s property rules |
| Chattel loan | Home only, no land; quicker; usually higher rates and shorter terms |
- Real-property mortgage: 30 years at an example 7.00% → about $798/month (principal and interest)
- Chattel loan: 20 years at an example 9.50% → about $1,119/month
Same money borrowed, about $321 more every month. Rates are examples only; real quotes vary by lender, credit and property.
What FHA checks on a manufactured home
For a standard FHA mortgage on a manufactured home, expect the lender to confirm that:
- The home was built on or after June 15, 1976 and has its HUD certification label (or replacement documentation).
- It has at least 400 square feet of living space.
- It sits on a permanent foundation that meets HUD’s Permanent Foundations Guide, usually confirmed by an engineer’s certification.
- It’s classified as real estate and is your primary residence.
- It hasn’t been moved from its original site (moved homes face extra hurdles).
- Base loan: $144,750
- Upfront FHA mortgage insurance (1.75%): about $2,533, usually added to the loan
- Principal and interest at an example 7.00% on the base loan: about $963/month
Annual FHA mortgage insurance, taxes and insurance come on top. Our FHA loan calculator adds them in for you.
Things that trip people up
- Missing HUD labels. If the labels are gone, you can usually order replacement verification, but it takes time. Ask early.
- Foundation certification. An older setup may need upgrades to meet the foundation guide.
- Title not converted. Many states require paperwork to turn the home’s title into real estate. Your title company or closing attorney handles this.
- Few lenders. Not every lender does manufactured homes. Shop around; our guide to comparing mortgage lenders helps.
- Appraisal comps. The appraiser needs similar sales nearby. In some areas these are scarce.
How to get started
- Find out about the land. Buying it, already owning it, or renting a lot? That decides your loan type.
- Check the home’s build date and HUD labels.
- Know your budget. Use our home affordability calculator and remember lot rent if you’ll lease land.
- Ask lenders directly whether they finance manufactured homes and which programs.
- Compare total costs, not just rates. Our closing cost calculator shows the upfront side, and our FHA loan requirements guide covers borrower rules.
FAQ
Can I get a 30-year mortgage on a manufactured home?
Yes, when the home and land are financed together as real property under programs like FHA or conventional loans. Chattel loans usually have shorter terms.
Can I get an FHA loan for a manufactured home on rented land?
A standard FHA mortgage generally requires the home to be real estate. FHA’s Title I program can finance a home on a leased lot if the lease meets its rules, but loan limits are lower and fewer lenders offer it.
Are mobile homes built before 1976 financeable?
Generally not with FHA, VA, USDA or conventional loans. Buyers usually need cash, seller financing or a specialty lender.
Is a manufactured home loan rate higher?
Chattel loan rates are usually higher than mortgage rates. Real-property mortgages on manufactured homes can be priced close to regular mortgages, though some lenders add small adjustments.
Do I need a permanent foundation?
For FHA and conventional real-property mortgages, yes. It must meet program standards, usually confirmed by a licensed engineer.
Sources: HUD Handbook 4000.1; HUD Permanent Foundations Guide for Manufactured Housing; 24 CFR Part 3280 (Manufactured Home Construction and Safety Standards); Fannie Mae Eligibility Matrix and Selling Guide; CFPB. This article is general education, not financial advice. Keys & Coffee is not a lender.

Written by
Shivam Kaushik· IMSHIVA
Founder & Director, QuibbleTech Solutions Pvt Ltd · Editor, Keys & Coffee
Shivam Kaushik is the founder of QuibbleTech Solutions Pvt Ltd and the editor of Keys & Coffee. He is not a licensed loan officer or financial adviser. Every guide here is written in plain English and checked against official sources such as the CFPB, HUD, Fannie Mae, Freddie Mac and the Federal Reserve. For advice on your own loan, talk to a licensed lender.
Keys & Coffee is an independent education site. We are not a lender or mortgage broker, we do not take loan applications or payments, and nothing here is financial advice. This site is not affiliated with Axia Home Loans, Axia Financial, LLC, or Planet Home Lending. Rates and rules change often — always confirm details with a licensed loan officer and check any lender on the NMLS Consumer Access site.
Keep reading
Investment Property Mortgage: Down Payment, Rates and Rules
Buying a rental? Here is how investment property mortgages work: the 15% and 25% down payment rules, why rates are higher, how…
Second Home Mortgage: Down Payment, Rules and How to Qualify
Buying a vacation home? Second home mortgages usually need 10% down and stricter rules than a primary home. Here's what lenders look…
Piggyback Loans (80/10/10) Explained: Skip PMI With 10% Down?
A piggyback 80/10/10 loan can help you skip PMI or avoid a jumbo loan. Here's how it works, a side-by-side cost comparison…