Jumbo Loans Explained: 2026 Limits, Requirements and Tips
Some mortgages are latte-sized; jumbo loans are the bucket with a handle. Here are the 2026 limits, what lenders want and how to tell if you even need one.
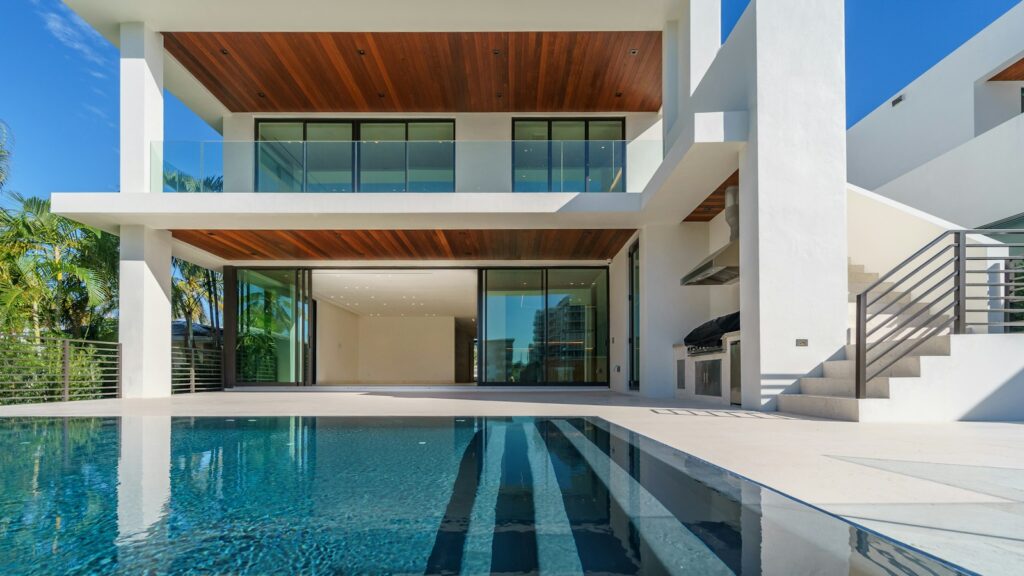
- A jumbo loan is a mortgage larger than the conforming loan limit set each year by the Federal Housing Finance Agency (FHFA).
- 2026 limits: the baseline conforming limit for a one-unit home is $832,750 in most of the U.S., and up to $1,249,125 in designated high-cost areas.
- Jumbo loans are not bought by Fannie Mae or Freddie Mac, so each lender sets its own rules.
- Expect tougher underwriting: often higher credit scores, bigger down payments and more cash reserves.
- Rates are not automatically higher — compare jumbo and conforming offers side by side.
Some loans are latte-sized. Jumbo loans are the bucket-of-coffee-with-a-handle size. If the house you want costs more than the typical mortgage limit allows, you are in jumbo territory. Here is what that means, what lenders look for and how to tell whether you need one at all.
What is a jumbo loan?
A jumbo loan is a type of non-conforming mortgage. “Conforming” loans meet Fannie Mae and Freddie Mac’s standards — including a maximum loan size. Fannie and Freddie buy conforming loans from lenders, which keeps money flowing. Loans above the limit cannot be sold to them, so the lender keeps them or sells them to private investors. That is why jumbo rules vary so much from lender to lender.
2026 conforming loan limits
Each year, the FHFA sets the conforming loan limits. For 2026:
| Area | One-unit limit (2026) |
|---|---|
| Most of the U.S. (baseline) | $832,750 |
| High-cost area ceiling | $1,249,125 |
| Alaska, Hawaii, Guam, U.S. Virgin Islands (baseline) | $1,249,125 |
The baseline rose by $26,250 from 2025’s $806,500. Limits are higher for 2- to 4-unit properties, and high-cost counties have their own figures somewhere between the baseline and the ceiling. Check your county on the FHFA website before assuming you need a jumbo.
Typical jumbo loan requirements
Because there is no Fannie/Freddie rulebook, jumbo lenders set their own standards. Common patterns include:
- Credit score: generally higher minimums than for conforming loans.
- Down payment: often larger than the 3%–5% possible on some conforming loans; many lenders want significantly more.
- Cash reserves: proof you have several months of mortgage payments saved after closing.
- Debt-to-income ratio: often stricter limits.
- Appraisal: some lenders require extra appraisal review — or a second appraisal — on larger loans.
- Documentation: thorough income and asset verification; self-employed borrowers should expect lots of paperwork.
Most jumbo loans must still meet the federal ability-to-repay rule, which requires lenders to make a reasonable, good-faith determination that you can afford the loan.
Jumbo vs conforming at a glance
| Conforming | Jumbo | |
|---|---|---|
| Loan size | Up to FHFA limit | Above FHFA limit |
| Rulebook | Fannie Mae / Freddie Mac standards | Each lender’s own |
| Minimum down payment | As low as 3% on some programs | Often higher; varies |
| Reserves | Sometimes required | Commonly required |
| Rates | Market-driven | Market-driven; can be higher, similar or lower |
| PMI with less than 20% down | Yes | Depends on lender; some avoid PMI with higher rates or require bigger down payments |
Fun twist: on a home priced at $1,040,937.50, putting 20% down leaves a loan of exactly $832,750 — the conforming limit. Spend a dollar more on the house (with the same 20% down) and the loan becomes jumbo. (Rates are illustrative only; taxes and insurance not included.)
Plug in your own price and down payment with our mortgage calculator, and test whether the payment fits your income with the home affordability calculator.
Ways to avoid a jumbo loan (if you want to)
- Bigger down payment. Bring the loan amount down to the conforming limit.
- Piggyback loan. Some buyers pair a conforming first mortgage with a second mortgage (for example, an 80/10/10 structure). The second loan usually has a higher rate, so compare carefully.
- Check your county’s limit. In a high-cost area, the conforming limit may be higher than you think.
- Government loans. FHA has its own county limits. VA loans have no maximum loan amount for borrowers with full entitlement, though lenders still apply their own underwriting. See our VA loan requirements guide.
Shopping tips for jumbo borrowers
- Get multiple Loan Estimates. Jumbo pricing varies widely by lender. Banks sometimes offer relationship discounts if you keep assets with them.
- Ask about points. On a big loan, one point is a big check. Our mortgage points guide shows how to calculate the break-even.
- Get fully pre-approved early. Jumbo underwriting takes longer. A pre-approval also strengthens your offer.
- Compare fixed vs adjustable options with care, and understand how an adjustable rate could change.
- Budget closing costs. Many costs scale with loan size — see closing costs explained.
Is a jumbo loan right for you?
A jumbo can make sense if you have strong credit, stable income, solid savings and a home price that genuinely requires it. It is less ideal if the payment would stretch you thin, or if you could reach a conforming loan with a modest adjustment to price or down payment. The best loan is the one you can comfortably pay every month, not the biggest one you can get approved for.
Getting ready to apply
Gather two years of income history (W-2s or tax returns), recent pay stubs, and several months of statements for every bank, brokerage and retirement account. Large deposits will need a paper trail, so do not move money around just before you apply. If you are self-employed, ask each lender up front which documents they want — it saves weeks of back-and-forth.
FAQ
What is the 2026 jumbo loan limit?
There is no “jumbo limit” — a jumbo is any loan above the conforming limit. For 2026, that is $832,750 for one-unit homes in most areas and up to $1,249,125 in high-cost areas.
Do jumbo loans have higher interest rates?
Not always. Jumbo rates depend on the lender and the market and can be higher, similar or occasionally lower than conforming rates. Compare actual offers.
How much do I need to put down on a jumbo loan?
It varies by lender, credit and loan size. Many lenders require more than conforming loans do, but requirements differ — ask several lenders.
Can I refinance a jumbo loan?
Yes. You can refinance into another jumbo, or into a conforming loan if your balance has dropped below the limit.
Do jumbo loans require PMI?
Policies vary. Some lenders offer jumbo loans with less than 20% down without traditional PMI, often with higher rates or stricter requirements; others simply require a larger down payment.
Sources: Federal Housing Finance Agency (Conforming Loan Limit Values for 2026); Fannie Mae and Freddie Mac (conforming loan standards); Consumer Financial Protection Bureau (ability-to-repay rule, Loan Estimate); U.S. Department of Veterans Affairs (VA loan limits); U.S. Department of Housing and Urban Development / FHA (FHA mortgage limits). Keys & Coffee is an independent education site, not a lender, and is not affiliated with Axia Home Loans. General information only.

Written by
Shivam Kaushik· IMSHIVA
Founder & Director, QuibbleTech Solutions Pvt Ltd · Editor, Keys & Coffee
Shivam Kaushik is the founder of QuibbleTech Solutions Pvt Ltd and the editor of Keys & Coffee. He is not a licensed loan officer or financial adviser. Every guide here is written in plain English and checked against official sources such as the CFPB, HUD, Fannie Mae, Freddie Mac and the Federal Reserve. For advice on your own loan, talk to a licensed lender.
Keys & Coffee is an independent education site. We are not a lender or mortgage broker, we do not take loan applications or payments, and nothing here is financial advice. This site is not affiliated with Axia Home Loans, Axia Financial, LLC, or Planet Home Lending. Rates and rules change often — always confirm details with a licensed loan officer and check any lender on the NMLS Consumer Access site.
Keep reading
Adjustable-Rate Mortgages (ARMs) Explained: How They Work, Caps and When They Make Sense
An ARM is like a gym membership with a great intro price: lovely at first, but you had better read what happens…
Conventional Loan Requirements 2026: Credit, Down Payment, DTI and Loan Limits
The conventional loan is the plain black coffee of mortgages: no government backing, no fancy add-ons and the most popular order on…
USDA Loans Explained: Zero Down Payment Home Loans for Rural (and Not-So-Rural) Buyers
No down payment, a fixed rate and a government guarantee. USDA loans are one of the best-kept secrets in home buying, and…